

Split Pay: Split Bills in Two
by Split Pay
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
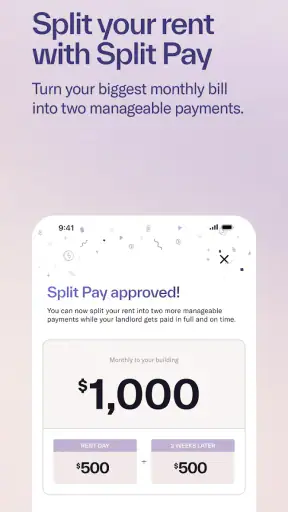
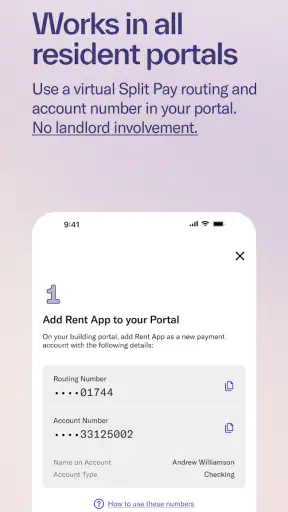
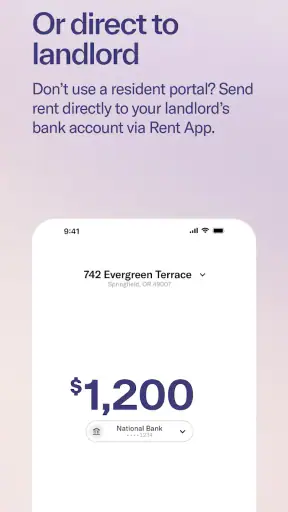
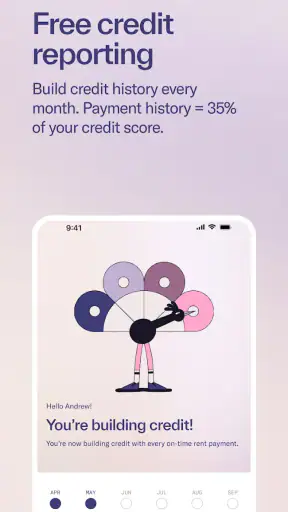
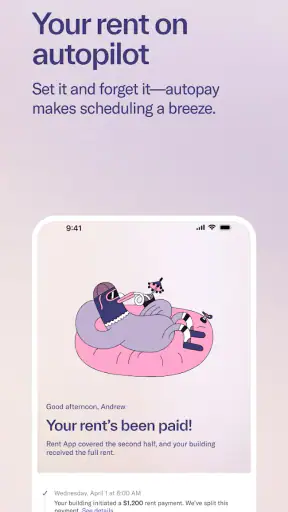
 Analysis by Getfullapps
Managing a large payment is rarely difficult because of the amount alone. The real problem is timing: rent is due before payday, a mortgage withdrawal lands during an expensive week, or a car payment competes with groceries and other automatic charges. Split Pay: Split Bills in Two is a finance app built around that specific pressure. I looked at it as a practical decision rather than as a general budgeting tool, and my main conclusion is simple: it makes the most sense for someone who needs breathing room around a major recurring bill, not for someone searching for a complete money-management system.
The app comes from Split Pay and is free to use. It sits in the finance category, carries an Everyone age rating, and has built a strong early reputation with a 4.8 average from around 3,300 ratings and more than 400 written reviews. It has also passed the 100,000-install mark, which gives me more confidence that it is being used beyond a tiny group of early adopters. Still, popularity is only one part of the decision. The important question is whether dividing a payment into two parts fits the way you already receive income and pay bills.
What I would check before relying on it
My first decision criterion would be the kind of bill involved. The store summary focuses on rent, mortgage, and car payments, so this is not an app I would choose simply to divide a restaurant check or track shared household spending. Its appeal is much narrower and more useful: it targets large obligations that can dominate a monthly budget. If that describes your situation, the app has a clear purpose. If your main challenge is knowing where every dollar goes, a traditional budgeting app is likely a better starting point.
The second criterion is whether splitting a payment actually improves your cash flow. A two-part schedule can help when income arrives at different points in the month. For example, I can imagine a renter being paid twice monthly, with one portion of rent handled after the first paycheck and the rest after the second. That arrangement may feel far more manageable than watching the entire housing payment leave at once. It does not reduce the total obligation, though, so I would treat the app as a timing tool rather than a way to make an unaffordable bill affordable.
That distinction matters. Anyone considering this app should write down the full amount of the bill, the dates income arrives, and the dates other essential charges are taken. Then I would ask whether two smaller withdrawals leave enough room for food, transport, utilities, and unexpected expenses. If the answer is no, splitting the payment could merely spread the stress across more days. The app may organize the payment, but it cannot replace a realistic monthly plan.
I would also consider how comfortable you are with a payment service handling an important recurring obligation. Rent, a mortgage, and a car payment are not casual purchases. Before making it part of my routine, I would read each confirmation screen carefully, check the destination and amount, and keep a separate record of the original due date. That habit is useful with any financial app, but it is especially important when the payment affects housing or transportation.
Another practical question is whether you need a one-off solution or a repeatable routine. Someone facing an unusually tight month may prefer to contact the biller directly and ask about available payment arrangements. Someone who regularly struggles because the bill is large compared with each paycheck may find a dedicated split-payment workflow more relevant. The difference is not about which option is more sophisticated; it is about whether the same timing problem keeps returning.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The experience feels focused rather than overloaded
What I like about Split Pay is the narrowness of its purpose. Instead of presenting a crowded dashboard filled with spending categories, investment charts, savings goals, and financial education, it points attention toward the payment that is causing the most pressure. That focus can be a strength for people who do not want to maintain a detailed budget every day. It also makes the app easier to explain to a partner or housemate: the goal is to arrange a major payment in two parts, not to redesign the household’s entire financial life.
The focused design also creates a useful mental separation. A conventional budget tells me what I spent; this type of tool is concerned with when a major charge is paid. Those are related but different jobs. I can use a budgeting method to understand affordability while using Split Pay to make the timing fit my income. That combination is more sensible than expecting one app to solve both problems equally well.
In an everyday scenario, imagine a household whose rent is due near the start of the month while one income arrives near the end of the previous month and another arrives halfway through the month. Paying the whole amount immediately may leave the household short for several days. A split arrangement could allow the household to align the payment with those two income events. The useful insight here is that the benefit comes from matching dates, not from the word “split” by itself. If both portions still leave the account at inconvenient moments, the arrangement has not solved the real issue.
Small routines make the arrangement safer
My strongest practical tip is to treat the first use as a test month. I would not begin with the most financially sensitive payment and then assume everything will work automatically. I would first map the expected dates, leave a cushion in the account, and confirm that both parts are visible in my personal records. After the first cycle, I would compare the actual experience with the plan: Did the timing reduce pressure? Did it create confusing overlaps with other bills? Did I need to move money manually?
A second tip is to keep the original biller’s information close at hand. Even if the app makes the split process convenient, I would still save the account reference, normal due date, and full amount somewhere secure. That makes it easier to verify what is being paid and to act quickly if a payment needs attention. This is a small workflow improvement, but it prevents the common mistake of treating a payment app as the only source of truth.
A third insight is that splitting can change how a household talks about responsibility. If two people contribute to rent or a car payment, dividing the schedule may make each person’s contribution easier to plan. It can also create disagreement if one person assumes the first portion is “their” share while the other sees the arrangement as a shared obligation. I would agree on the full amount, the two dates, and what happens if one person’s income is late before setting up a recurring routine.
Where the app is a better fit than ordinary alternatives
Compared with paying the entire bill directly from a bank account, the main advantage is control over timing. Direct payment is simple, familiar, and often the least confusing choice when the money is already available. Split Pay becomes more attractive when the direct option forces a large withdrawal at the wrong point in the month. In that situation, the app addresses a specific friction that a normal bank transfer does not necessarily address.
Compared with asking a landlord, lender, or finance company for a custom arrangement, an app may feel more convenient for a recurring personal workflow. A formal arrangement with the biller can be preferable when the payment is unusually large, when hardship is involved, or when you need written terms. Split Pay is better suited to ordinary cash-flow management where the total bill remains within reach and the problem is scheduling rather than inability to pay.
Compared with a credit card, the appeal is avoiding the temptation to use revolving credit simply because a large bill arrives at an inconvenient time. A card can provide flexibility, but it can also turn a timing problem into a balance that lasts longer and costs more. I would not assume that any split-payment service is automatically free of risk, but the basic decision principle is clear: do not use a payment schedule to hide debt that you cannot comfortably cover.
Compared with a general budgeting app, this product is more direct but less comprehensive. A budget can show whether rent, a mortgage, or a car payment is consuming too much of the month’s income. Split Pay is more useful after I already understand the obligation and only need a practical way to divide its timing. People who want transaction categorization, long-term savings planning, or a complete household overview should look elsewhere or use this app alongside another method.
Limitations I would take seriously
The biggest limitation is the narrow scope. The app’s focus on rent, mortgage, and car payments is helpful when one of those bills is the problem, but it may feel restrictive if your financial pressure comes from utilities, tuition, medical costs, subscriptions, or irregular expenses. I would not install it expecting a universal bill-splitting solution. Its value depends heavily on whether your largest recurring payment matches the job it is designed to handle.
There is also a behavioral risk. Two payment dates can make a bill feel smaller even though the total is unchanged. That can encourage overconfidence, especially for someone who checks only the next withdrawal instead of the complete monthly commitment. My workaround would be to record the full amount in my budget and think of the two portions as one bill with two scheduled moments. That keeps the convenience without losing sight of the obligation.
Another possible source of friction is coordination. A split schedule can be easy for one person to understand but harder for a household with several accounts, irregular paydays, or shared responsibilities. I would avoid setting it up immediately before a due date, when there is little time to correct an error. A calm setup earlier in the cycle is safer than trying to solve a cash-flow problem at the last minute.
The current version is 2.0.4, and the app was released on December 5, 2023. Those details suggest a relatively young product compared with long-established finance platforms, so I would pay attention to how comfortably it fits my own routine rather than assuming it offers the maturity of a full-service banking tool. That is not a criticism of the concept; it is a reminder to test the workflow, keep records, and avoid depending on any single app without a backup plan.
What switching would involve
Moving from direct payment to a split arrangement is not just a matter of installing an app. I would first review automatic payments already scheduled through my bank or biller so I do not accidentally create a duplicate charge. I would then note the normal due date, the total amount, and the account that currently funds the payment. This preparation is especially important for housing and vehicle obligations, where a missed or duplicated payment can create serious inconvenience.
I would also decide how to monitor the new routine. A simple calendar reminder for both portions is enough for many people. For a shared household, I would add the dates to a common calendar and agree on who checks that the full amount is covered. This is one of the less obvious trade-offs: the app may reduce the size of each individual payment, but it can increase the number of dates that need attention. Convenience improves only when the new schedule is visible and understood.
If the arrangement does not work, I would not keep it merely because changing back feels inconvenient. The correct alternative might be returning to a direct bank payment, adjusting the household budget, changing the bill’s due date with the provider, or seeking formal assistance. A useful financial tool should make the situation clearer. If it makes the payment history harder to follow, the usual alternative may be better.
The free price makes trying it less intimidating, but “free” should not replace careful checking of the actual payment flow. I would review the final amount, timing, and confirmation details before committing to a major recurring bill. I would also keep enough funds available for both parts rather than transferring money at the last possible moment. That habit protects against the practical problem that affects many payment systems: a plan can be correct while the account balance is not ready when the transaction occurs.
Who should use it, and who should skip it
I would recommend giving Split Pay a serious look if you receive income in two predictable cycles, have one large recurring payment that repeatedly arrives at an awkward time, and want a focused tool rather than a complete budget. It may also suit couples or housemates who need a clearer rhythm for contributing toward a major shared obligation. The best users are not necessarily people with no money; they are people whose money arrives on a schedule that does not line up neatly with the bill.
I would be more cautious if your income is irregular, your account balance is already unstable, or you are using the app to cover a permanent shortfall. In those cases, splitting a payment may postpone the difficult moment without improving the underlying position. I would also skip it if you need detailed spending analysis, debt payoff planning, investment tracking, or broad bill management. A dedicated budgeting or banking solution will probably provide more value for those needs.
Age and accessibility are straightforward here: the app is rated for Everyone, which makes it approachable for a broad audience. That does not mean every financial situation is equally suitable. A first-time user should still involve a trusted household member when the payment affects shared housing or transportation, and anyone managing a mortgage or vehicle obligation should preserve the original lender or provider records.
My recommendation after weighing the trade-offs
My recommendation is conditional but positive. Split Pay is worth trying when your central problem is the timing of a rent, mortgage, or car payment and you can already afford the full amount. Its strongest quality is that it concentrates on a real everyday pain point instead of asking users to build an elaborate financial system. The good rating from thousands of users and its growing install base support the idea that the concept is resonating, but I would still judge it by one practical test: does the two-part schedule leave my month easier to manage without making the payment history confusing?
I would use it as one piece of a broader routine, not as a substitute for a budget or emergency cushion. Before switching, I would compare the two dates with every other automatic charge, record the complete bill amount, and test the process with enough balance available. Afterward, I would review the first cycle and keep the arrangement only if it genuinely improves cash flow. That approach turns the app from a hopeful shortcut into a controlled experiment.
For someone who wants a simple way to divide a major recurring payment, the key advantage is better timing, not lower cost or lower responsibility. For someone who needs a complete view of their finances, a conventional budgeting app or direct bank tools will likely be more appropriate. I would recommend Split Pay to the first group, with those safeguards in place, and advise the second group to choose a broader alternative instead.
In short, this is a specialized finance app with a sensible purpose. It can make a large monthly obligation feel more compatible with a twice-monthly income pattern, especially when the household plans the dates carefully. It cannot solve insufficient income, replace communication between co-payers, or remove the need to verify important transactions. Used for the problem it actually targets, it is a focused and potentially helpful option from Split Pay; used as a cure for deeper financial strain, it is the wrong tool.
Pros
- Simple interface makes splitting shared expenses quick and easy.
- Supports uneven bill splits when people owe different amounts.
- Useful for dinners, trips, rent, and recurring group expenses.
- Reduces calculation mistakes when dividing totals and tips.
- Helps keep personal and group spending organized in one place.
Cons
- All participants may need the app for the smoothest experience.
- Payment collection may depend on external apps or supported services.
- Limited usefulness if your group rarely shares expenses.
- Manual entry is still required when receipts cannot be imported.
- Privacy-conscious users may hesitate to store financial details in the app.
FAQs for Split Pay: Split Bills in Two
What is Split Pay: Split Bills in Two, and how does it work?
Split Pay: Split Bills in Two is designed to help you divide shared expenses between two people without calculating everything manually. After entering the bill amount, you can usually assign the total equally or adjust the split when one person paid for extra items. The app is particularly useful for meals, household costs, trips, subscriptions, and other everyday expenses shared with a partner, friend, or colleague.
Can I split a bill unevenly with Split Pay?
Yes, the app is intended for situations where a simple 50/50 division is not enough. You can enter the total and modify the amount each person should contribute, which is helpful when people ordered items with different prices or when one person already covered part of the bill. Before confirming the result, check that both assigned amounts add up to the original total, especially when tips, taxes, or discounts are included.
Does Split Pay support tips, taxes, discounts, or additional charges?
Split Pay can be useful for handling the final amount of a bill, including tips, taxes, delivery fees, or discounts, as long as those values are included in the total you enter. Depending on the version available on your device, it may not automatically identify these charges from a receipt or calculate them separately. For the most accurate result, review the receipt first and enter the complete amount you want to divide.
Can I use Split Pay for more than two people or recurring expenses?
The app’s main purpose is splitting a bill between two people, so it is best suited to couples, roommates, friends, or two colleagues sharing a payment. It may not replace a full group-expense manager for large dinners or trips involving several participants. Likewise, recurring expenses may need to be entered manually each time unless your installed version provides history, saved calculations, or another tracking feature.
Is Split Pay: Split Bills in Two free, and does it require an internet connection?
Availability, pricing, advertisements, and optional purchases can vary according to the Android or iOS version and the developer’s current release. Basic bill calculations generally do not require an internet connection, which makes the app convenient in restaurants or while traveling. However, downloading updates, viewing store information, or using any cloud-based feature will require connectivity. Check the official app-store listing for the latest permissions and pricing details.

Split Pay: Split Bills in Two
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@rent.app, visit https://rent.app, or review their https://rent.app/privacy/.










